TL;DR
Noodles & Company raised its annual guidance after a strong first quarter with a 9.1% increase in systemwide same-store sales. The company's two-year turnaround effort is paying off, with improvements in menu, operational execution, and marketing contributing to the positive results.
Noodles & Company on Wednesday raised its guidance for the year on better-than-expected results, saying its two-year turnaround effort is paying off.
The fast-casual chain said same-store sales in the first quarter were up 9.1% systemwide, including a 9.4% increase at company-owned restaurants and an 8% increase at franchised units. The company said it has delivered positive comparable sales for the last 16 months consecutively.
Traffic at company units was up 4.8%, and the average check increased 4.4%, which reflected a 2% menu price increase and the rest from guests choosing higher-priced items.
Restaurant-level margins grew by 460 basis points to 14.9%, compared with 10.3% a year ago.
The company also narrowed its net loss to $3.4 million in the March 31-ended quarter, compared with a net loss of $9.1 million in the first quarter last year. Revenues remained flat at $123.8 million.
Noodles is benefitting from the closure of 33 underperforming company restaurants last year, and another 20 closures in the first quarter this year, along with the shuttering of three franchised units.
The company has said it plans to close another 10 to 15 restaurants in 2026, as it continues to review the portfolio. Another two franchised units are also expected to shutter.
The closures have driven sales to nearby locations and boosted off-premise sales, which has ultimately improved unit profitability.
CEO Joe Christina, however, said the improved results were less about the restaurant closures and more about improvements in the business, including “doing small things right every day, with those small improvements adding up to meaningful wins.”
He credited Noodles’ overhaul of the menu last year, as well as an ongoing strengthening of operational execution and more effective marketing.
“Put simply, we are operating better restaurants today than we were a year ago,” Christina said.
He also said the chain’s value-positioned Delicious Duos, pairing an entrée and side for $9.95, have also continued to drive traffic, as did the return of the fan-favorite Steak Stroganoff and a Chili Garlic Ramen, which was one of the most successful limited-time offers in brand history.
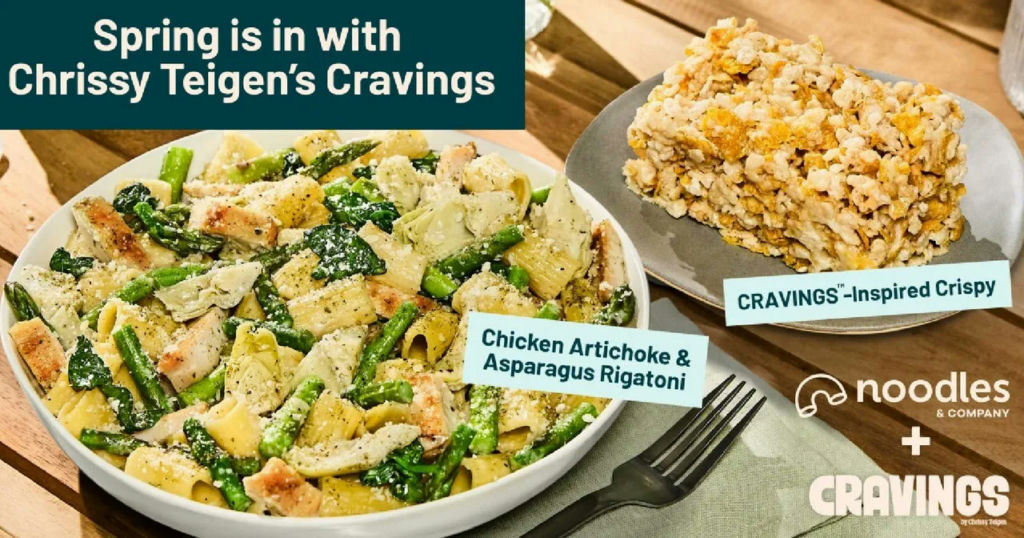
On Wednesday, Noodles launched a collaboration with model/actress/entrepreneur Chrissy Teigen featuring the limited-time dish Chicken Artichoke & Asparagus Rigatoni in a light garlic-herb sauce. It is paired with a dessert called Crispy, a treat with corn flakes, peanut butter and butterscotch chips inspired by Teigen’s Cravings Glorious Golden Cookie Mix. The pair is priced at $16.45.
As a result of the stronger-than-expected quarter, the company is projecting same-store sales growth of between 7% to 10% this year, with revenues of $483 million to $498 million.
Meanwhile, Noodles is still considering a review of strategic alternatives to maximize stockholder value, including a refinancing of debt, refranchising or the sale of all or part of the business, along with other options. The review is ongoing, but the status of the effort was not addressed during the earnings call.
In this story
This story was originally published by Lisa Jennings in Nation's Restaurant News on May 6, 2026. Burnaze summarizes and links to the original reporting.
Read the full story at Nation's Restaurant NewsLiked this? Get the week's franchise news, explained
- Sunday 8 AM ET weekly + a monthly deep dive
- Sections picked for the industries you follow
- Every claim linked to its source. Free.